For nearly four years, Berkshire Hathaway (NYSE: BRK.A) (NYSE: BRK.B) sat on a massive cash pile, peaking at a record $397 billion. But the second quarter of 2026 marked a turning point. The conglomerate's liquidity dropped to roughly $366 billion, a reduction of $31 billion in just three months 📉. While the majority of the cash remains on the sidelines, this move signals a clear shift in strategy from CEO Greg Abel. It's a signal many long-term investors have been waiting for, suggesting that management sees value opportunities in the current market landscape. 📌

Where the $31 Billion Went: A Closer Look at the Trades 🕵️♂️
The most significant deployment was a massive expansion in Alphabet (NASDAQ: GOOGL) (NASDAQ: GOOG). Berkshire increased its position by over $17 billion, bringing the total stake to nearly $36 billion. This makes Alphabet the conglomerate's third-largest holding, surpassing even its long-held position in Coca-Cola. This is a massive bet on the future of AI and digital advertising.
Beyond the tech giant, Abel added several other key positions:
- Delta Air Lines (NYSE: DAL): Added 17.5 million shares, bringing the total to 57.3 million. This is a bullish signal for the travel and consumer economy ✈️.
- Macy's (NYSE: M): More than doubled its stake, adding 4.3 million shares. This is a value-oriented bet on the beaten-down retail sector 🛍️.
- Lennar (NYSE: LEN) & New York Times (NYSE: NYT): Both saw their positions expanded, though with smaller capital outlays.
Perhaps the most interesting move was the $4.5 billion used to repurchase Berkshire's own stock. This is a massive jump from the mere $235 million spent in Q1 and signals that management believes the stock is undervalued. It ended a six-quarter hiatus in buybacks, showing a renewed confidence in the company's intrinsic value. This is a classic Buffett-esque move, suggesting that the 'purchase price' is the most important factor. 💡
This shift in strategy is a major talking point. Let's hear from the bulls and bears on what this really means for Berkshire's future. 🐂 vs 🐻
The Great Debate: Capital Deployment vs. Holding Power 💰⚖️
The decision to deploy capital after such a long period of inactivity is generating significant discussion among investors. Is this the start of a new era of aggressive investing, or is it just a minor recalibration? The market is split on what this means for the future.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| DAL (Delta) | $80 | 13.30 | 2.40 | 20.12% | 7.92% | 18.70% |
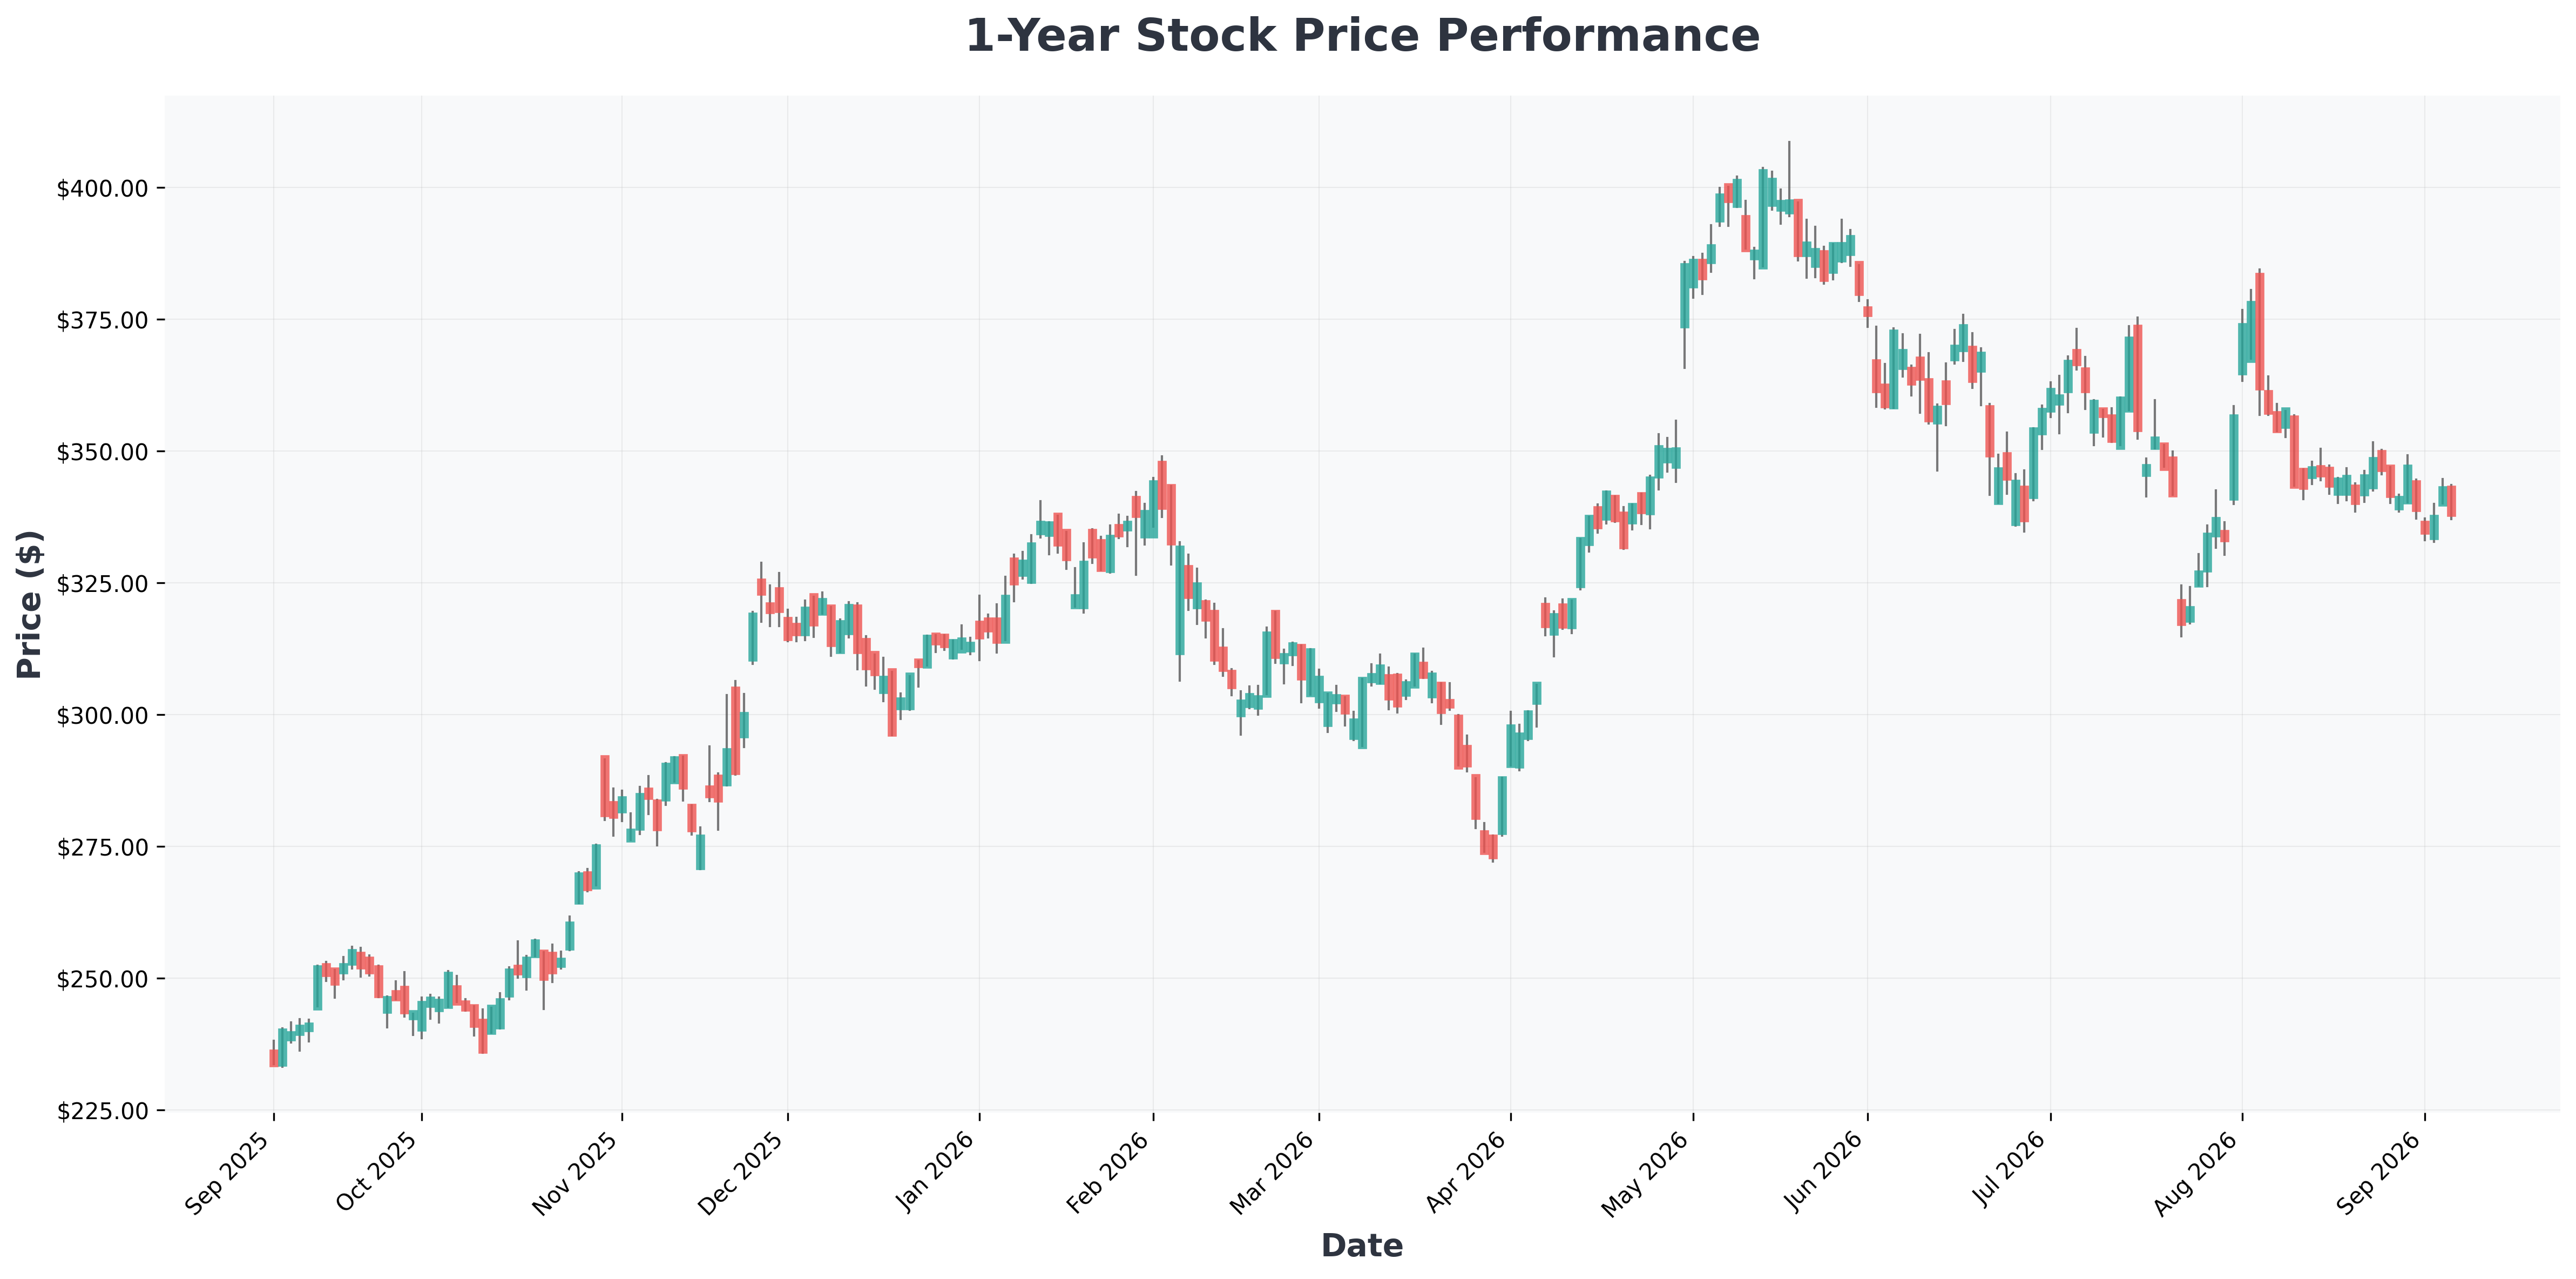
| GOOG (Alphabet) | $335 | 16.83 | 6.59 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $338 | 16.97 | 6.65 | 48.68% | 34.03% | 24.20% |
| LEN (Lennar) | $84 | 13.10 | 0.93 | 7.37% | 5.28% | -5.20% |
| M (Macy's) | $23 | 9.52 | 1.25 | 14.36% | 1.76% | 2.10% |
| NYT (New) | $67 | 28.03 | 5.31 | 19.72% | 17.12% | 11.30% |
Scenario Analysis & The Road Ahead 🔮
Best-Case Scenario: The Alphabet bet pays off handsomely as AI monetization accelerates, and the airline and retail positions recover strongly. The stock buyback proves timely, boosting earnings per share and rewarding patient shareholders. This could mark the beginning of a new growth era for Berkshire, with Abel successfully transitioning from Buffett's capital-preservation mode to a more dynamic allocation strategy.
Worst-Case Scenario: The market experiences a significant correction, and these new positions, particularly in cyclical sectors like airlines and retail, suffer sharp drawdowns. The cash pile, which was a defensive fortress, is now partially gone, reducing Berkshire's ability to capitalize on a true crisis. Critics might argue that the timing was premature and that Abel should have waited for a better entry point.
| Scenario | Key Drivers | Potential Impact on BRK.B |
|---|---|---|
| Bull Case 🚀 | AI-driven growth at Alphabet, resilient consumer spending, successful buybacks | Stock outperforms the S&P 500, narrowing the valuation gap with its historical average. |
| Bear Case 🐻 | Economic recession, poor performance in cyclical stocks, missed opportunity for a cheaper entry point | Stock underperforms, and the market questions Abel's capital allocation skills. |
| Base Case | Moderate growth from new positions, continued buybacks at a measured pace | Stock delivers steady, market-matching returns with lower volatility. |
Conclusion: The Q2 moves are a clear indication that Greg Abel is putting his own stamp on Berkshire. He is not simply hoarding cash but is willing to make bold bets when he sees value, including on the company itself. The patience he has shown over the past few years is now being paired with decisive action. For investors, this suggests a more dynamic future for Berkshire, one that may offer more growth opportunities than in the recent past. However, it also introduces new risks that were previously mitigated by the enormous cash buffer. If you're looking to understand the broader market context around these moves, you might find our analysis of Dow Jones futures and market reactions helpful. As always, consider the risks and how this fits into your overall portfolio strategy. For those focused on tech, also check out this perspective on quantum computing's emerging threat to Big Tech.