Berkshire Hathaway (BRK.A) (BRK.B) is sitting on a mountain of money that keeps getting taller. The company ended Q3 2026 with a record ~$397 billion in cash and Treasury bills, up from ~$348 billion a year earlier and just $129 billion three years ago. 📌
This raises two critical questions: Why does the pile keep growing, and where might new CEO Greg Abel finally put it to work, especially in artificial intelligence?
Why the Cash Keeps Piling Up 💰
The simplest reason is that Berkshire has been a net seller of stocks for over a dozen consecutive quarters, unloading more than $150 billion in equities since late 2022. It trimmed its massive Apple stake and has struggled to find bargains in a market trading near record highs. Buffett built his career on refusing to overpay, and Abel is carrying that discipline forward.
Meanwhile, cash is no longer dead money. With interest rates elevated, Berkshire parks most of its hoard in short-term Treasury bills generating enormous income. In fact, the interest alone earns more annually than most S&P 500 companies make in total profit. So the pile grows from two directions: Berkshire keeps selling stock, and the cash compounds. 📈
This issue has the market divided. Here's how the bulls and bears are sizing up Berkshire's next big move:
Which AI Stock Might Be Next? 🎯
If we had to name the most logical candidate, it would be Taiwan Semiconductor Manufacturing (TSM). It fits the Berkshire mold almost perfectly: a dominant, wide-moat business manufacturing nearly every advanced AI chip on earth, gushing cash, and trading at a fair valuation—far cheaper than most AI stocks. Best of all, Berkshire already knows it. The company bought a stake in late 2022, then sold it within months, citing geopolitical tension around Taiwan.
Here is why that history matters. Abel has shown more willingness than Buffett to tolerate that kind of risk, and TSM has only grown more essential to the AI economy since Berkshire exited. Revisiting a wonderful business it once owned—now at the heart of the biggest tech shift in a generation—would be a very Berkshire thing to do.
Microsoft (MSFT) , with its enterprise moat and OpenAI stake, is another name that fits the mold, one Buffett largely avoided due to his friendship with Bill Gates. But TSM remains the cleaner fit.
Key Financial Snapshot
| Metric | Berkshire (BRK.B) | Taiwan Semi (TSM) | Microsoft (MSFT) |
|---|---|---|---|
| Market Cap | $1.1T | ~$1T | $3.4T |
| Gross Margin | 23.7% | ~60% | 67.9% |
| Dividend Yield | N/A | ~1.3% | 0.79% |
| 52-Week Range | $455 - $517 | $150 - $220 | $349 - $554 |
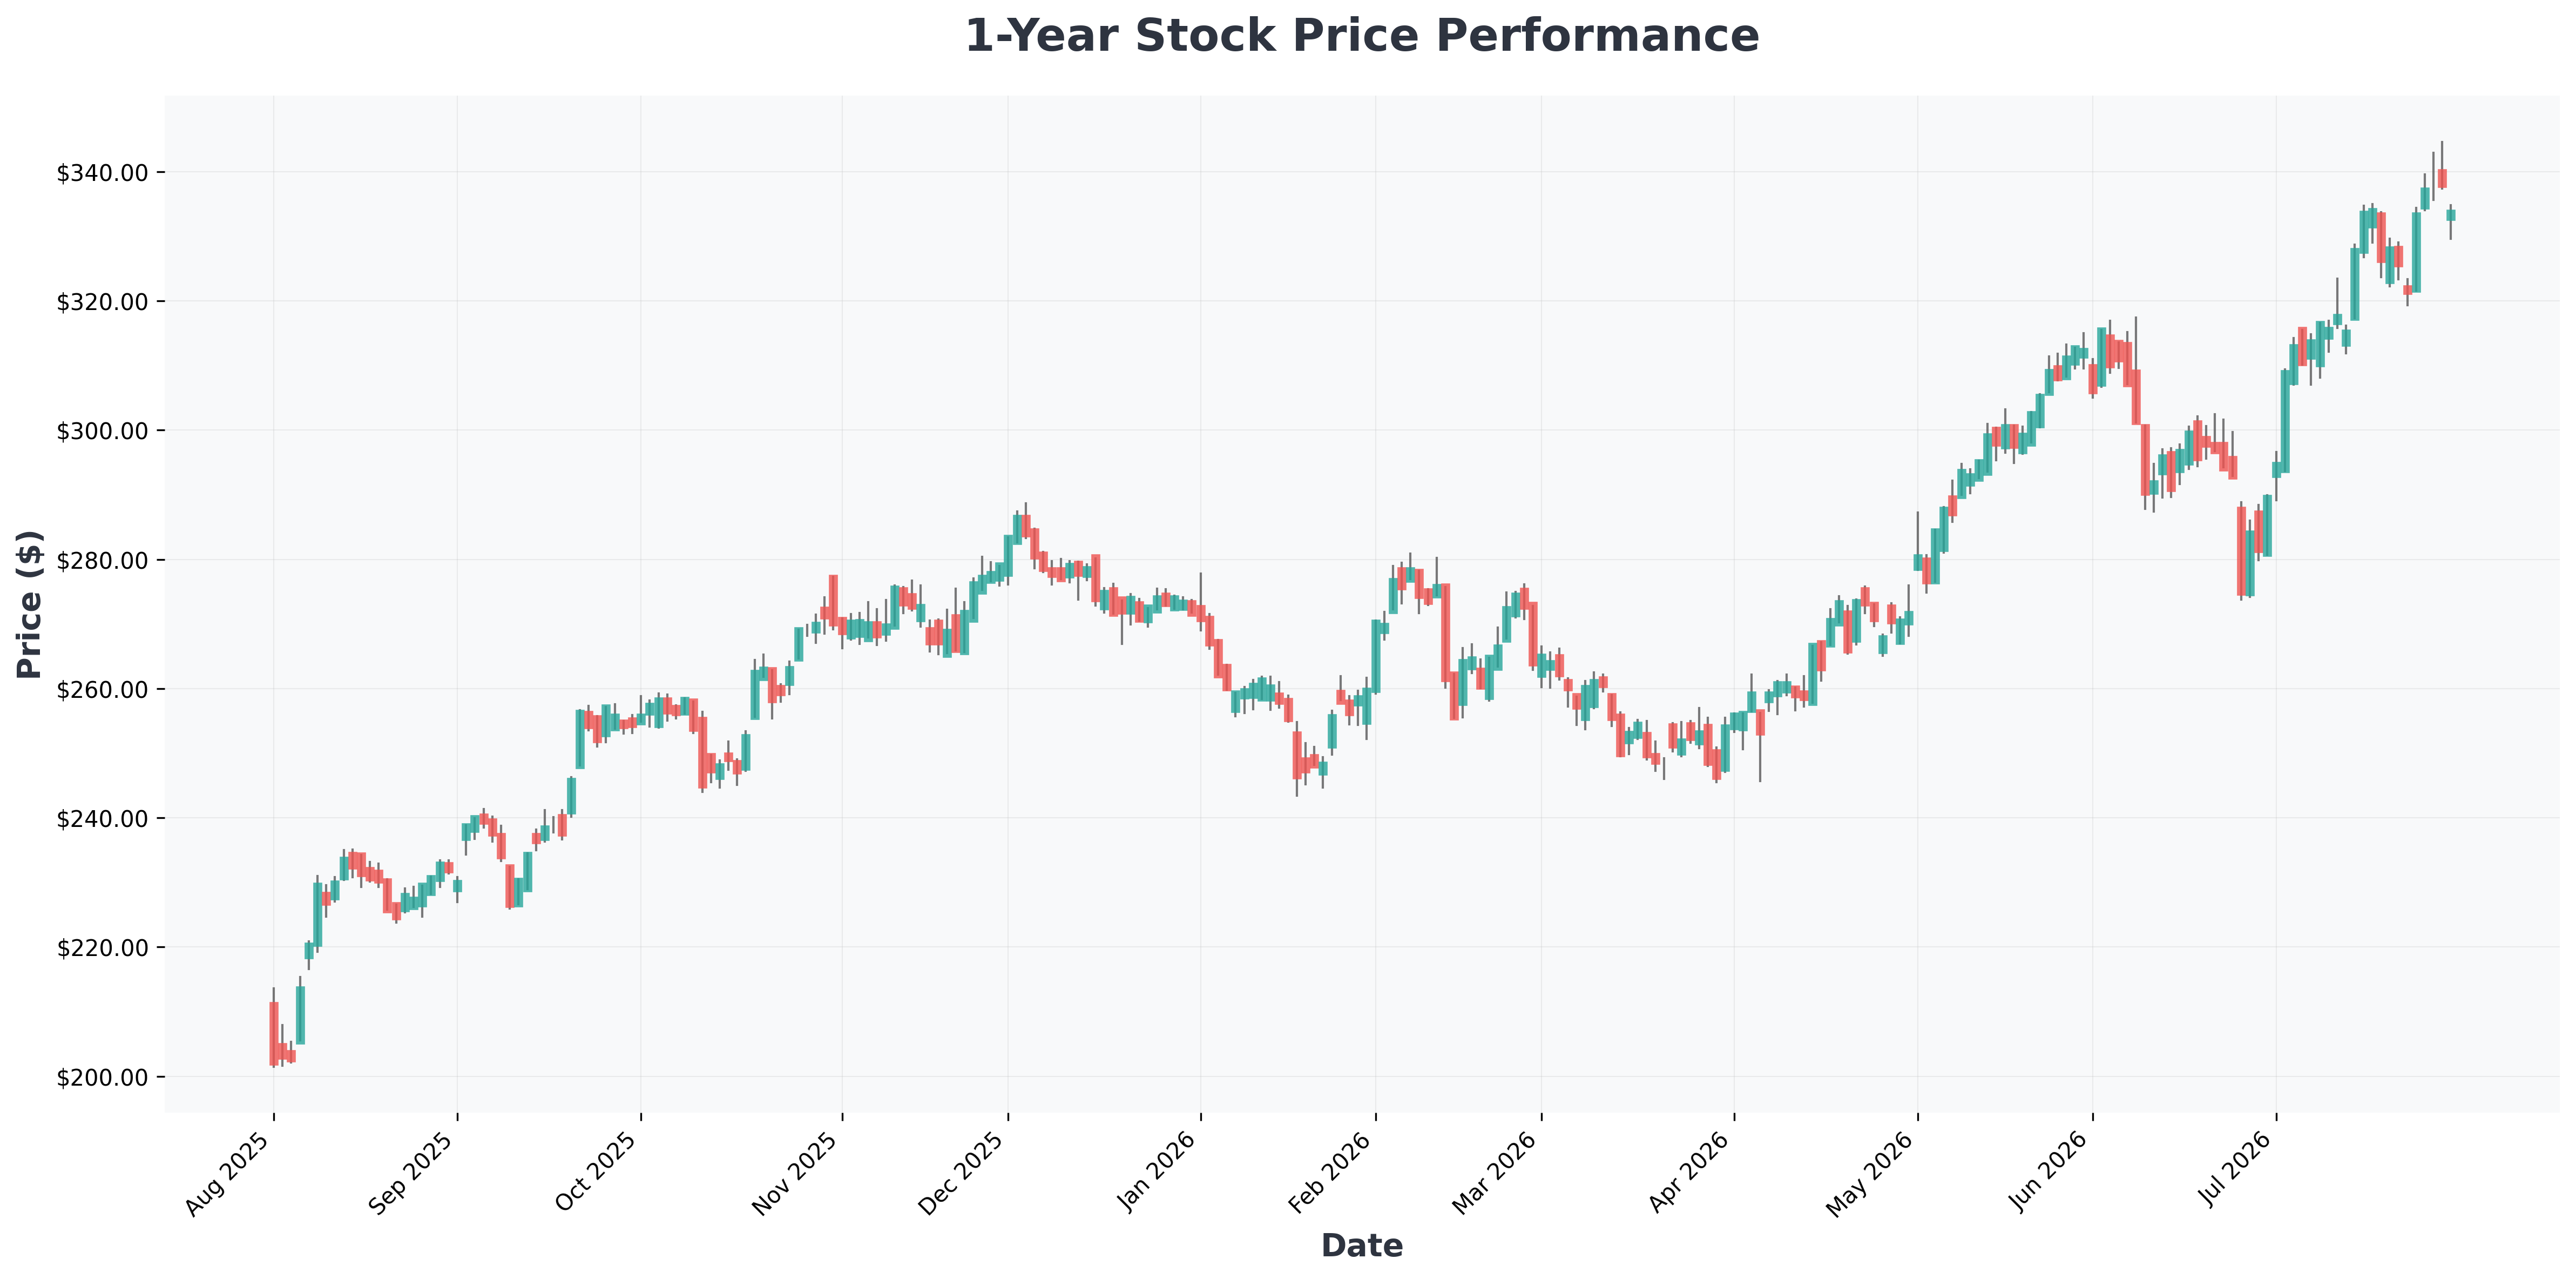
Pro Insight: From a technical standpoint, TSM has established a strong support base near its 50-day moving average, and any pullback toward that level could present a classic 'buy-the-dip' opportunity for long-term investors. Historically, whenever Berkshire has re-entered a position it previously exited, the second entry has often been at a more favorable valuation.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $301 | 34.47 | 41.50 | 148.75% | 32.62% | 16.40% |
| TSM (Taiwan) | $408 | 35.85 | 85.02 | 39.97% | 60.34% | 36.00% |
| GOOGL (Alphabet) | $354 | 17.77 | 6.96 | 48.68% | 34.03% | 24.20% |
| GOOG (Alphabet) | $354 | 17.77 | 6.96 | 48.68% | 34.03% | 24.20% |
| MSFT (Microsoft) | $464 | 25.83 | 7.78 | 34.04% | 45.11% | 17.70% |

The Caveat Worth Naming ⚠️
This is a prediction, not a certainty. The same geopolitical worries that pushed Buffett out of TSM haven't disappeared, and Abel may simply keep hoarding cash until a 'fat pitch' arrives. The real lesson is less about guessing the exact trade and more about the kind of business Berkshire hunts for: durable, cash-rich, and fairly priced.
Berkshire's swelling cash pile reflects patience and discipline, not panic. It gives Abel enormous firepower for the day the right opportunity appears. When he does deploy, expect a wonderful business bought at a sensible price. Among AI-linked names, TSM fits that description better than almost anything else. My honest read is that watching how Berkshire spends this cash will reveal a great deal about how the post-Buffett era intends to invest. 🚀