Nike's S&P 100 Exit: A Warning Shot for Dow Jones Investors 🚨
S&P Global dropped a quiet bombshell on index watchers: Nike (NKE) will be removed from the S&P 100 effective Sept. 21, alongside Honeywell Aerospace, Simon Property Group, and Colgate-Palmolive. Taking their seats: Dell Technologies, Palo Alto Networks, Arista Networks, and Sandisk.
For most investors, an index reshuffle is background noise. But for Nike, this is a flashing red signal. The S&P 100 is not a pure market-cap ranking — it's a curated list of blue chip leaders across sectors. Nike's removal means the index committee no longer views the company as a sector leader. That raises an uncomfortable question: if Nike isn't good enough for the S&P 100, how long until the Dow Jones Industrial Average (^DJI) shows it the door?
Let's break down the mechanics, the risks, and what it means for your portfolio. 📌
Why Nike Lost Its Seat — And Why It Matters
The S&P 100 isn't the 100 largest S&P 500 companies by market cap. It's a hand-picked roster of megacap and large-cap blue chips that represent their industries. Nike stayed in for years on brand prestige, not size. That prestige has evaporated.
Nike is now the 213th-highest-weighted company in the S&P 500 and the lowest-ranked component in the iShares S&P 500 100 ETF. Meanwhile, Dell, Palo Alto, Arista, and Sandisk have surged into the top 50 by market cap — they earned their seats.
The Fundamental Deterioration
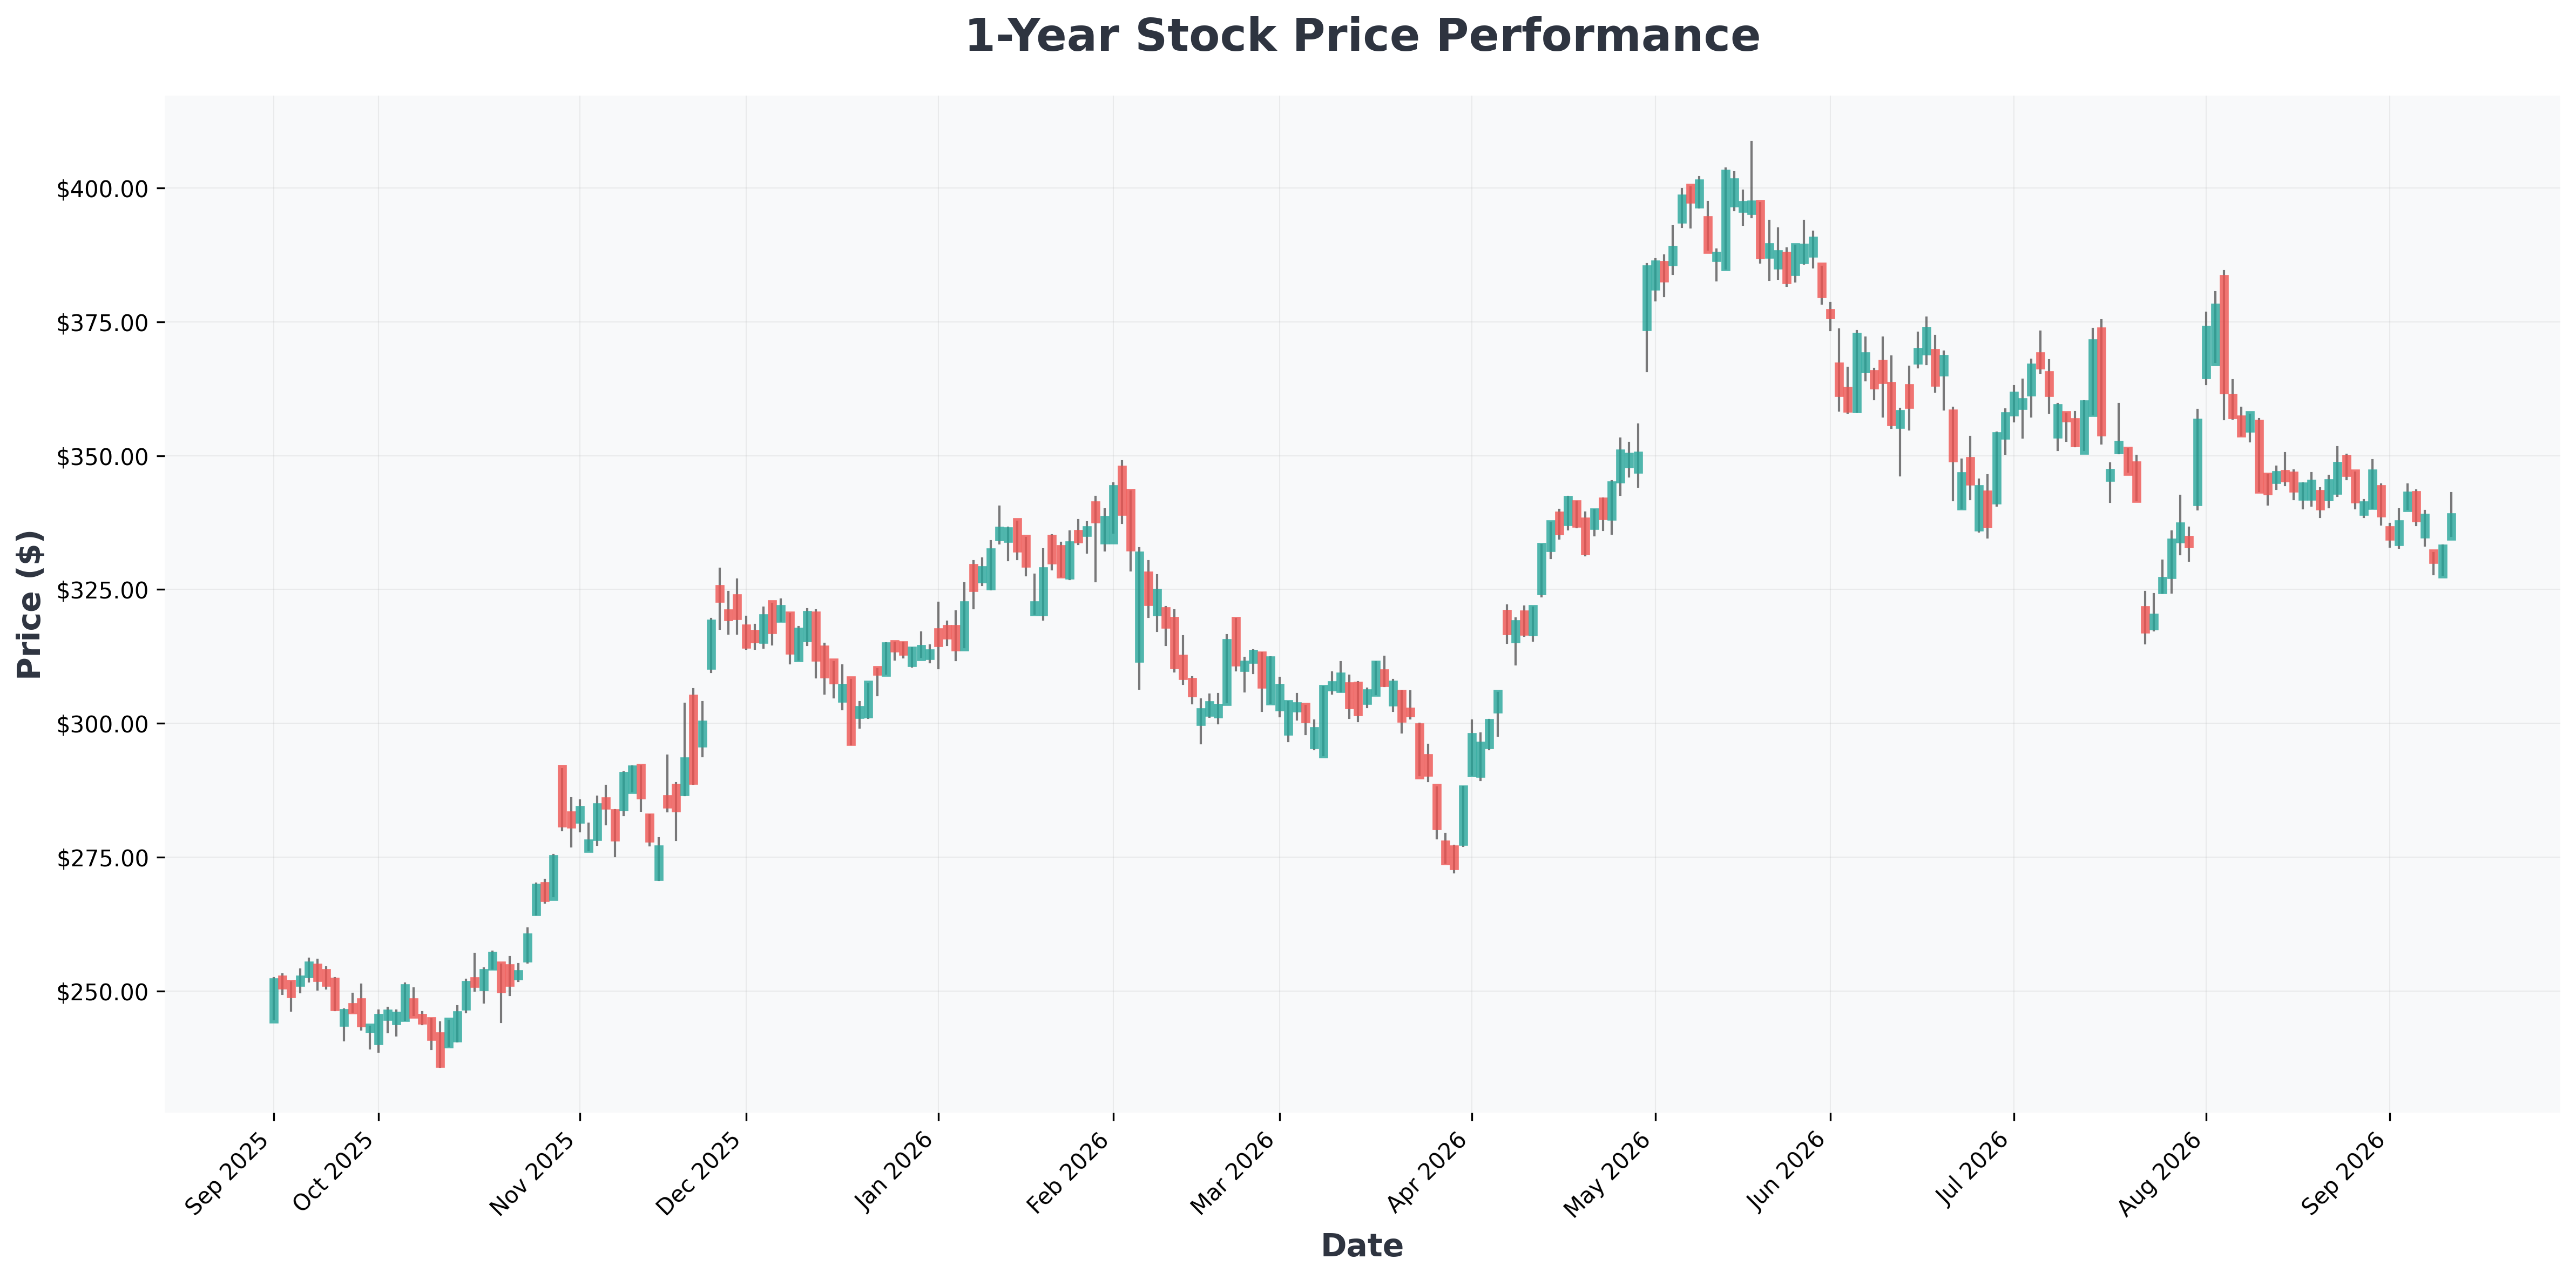
The chart tells a brutal story. Nike sits at its lowest level in over a decade. Revenue and earnings have declined in recent years, and operating margins have collapsed from the low-to-mid teens pre-pandemic to under 9% today. The laundry list of problems includes:
- Supply chain and corporate strategy missteps
- Slowing growth in China
- Tariff headwinds
- Domestic consumer spending pressure
- Intensifying competition from On, Hoka, and Adidas
The Turnaround Plan: Win Now
Nike's "Win Now" plan has implemented cost cuts and rebalanced wholesale versus direct-to-consumer. For fiscal 2026 (ended May 31), wholesale revenue grew 4% year over year, with double-digit growth in North America. But the structural challenges — competition, China, discretionary spending — remain unresolved.
If you're tracking how institutional money rotates out of underperforming consumer names, the recent McCollum Christoferson exit from Simply Good Foods offers a useful parallel on how smart money reads deteriorating fundamentals. 📊
Market participants are sharply divided on whether Nike's index troubles are a buying opportunity or a final warning. Here's how the two camps see it:
The Dow Jones Question: How Real Is the Risk?
The Dow is a price-weighted index of just 30 components — far more exclusive than the S&P 100, Nasdaq-100, or S&P 500. With Alphabet replacing Verizon in June, Nike is now the lowest-ranked component in the Dow, making it the most likely candidate for replacement.
The Dow has pivoted hard toward tech to reflect the modern economy — adding Nvidia and Amazon in 2024, and Alphabet in 2026. Massive names are waiting in the wings:
| Candidate | Why They Fit the Dow |
|---|---|
| Broadcom | Semiconductor and AI infrastructure leader |
| Meta Platforms | Megacap tech with global ad dominance |
| Tesla | EV and energy innovation flagship |
| SpaceX (or merged Tesla-SpaceX) | Aerospace and next-gen tech exposure |
Nike's dividend pedigree — 24 consecutive years of increases at a 4.3% yield — traditionally would have protected its Dow seat. But that criterion carries less weight today: Alphabet and Nvidia both yield under 0.5%, and Amazon pays no dividend at all.
The Dividend Pressure Point
Nike's payout could come under pressure if dividend expense absorbs too much free cash flow. With FCF already compressed by weak margins and turnaround spending, the dividend coverage ratio is worth monitoring each quarter.
Technical Read
NKE has been printing lower highs and lower lows since 2021, and the $36.55 area marks the 52-week low — a level that now acts as the last line of defense. A sustained break below it would likely accelerate index-exclusion flows, while reclaiming the $45–$48 zone would be the first real signal that a base is forming.
For investors weighing high-yield alternatives with stronger fundamentals, our AGNC vs. Starwood Property Trust comparison breaks down two income plays with very different risk profiles. 📈
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| SNDK (Sandisk) | $1,633 | 22.12 | 15.47 | 91.64% | 78.47% | 371.60% |
| NKE (Nike,) | $37 | 17.52 | 3.67 | 22.14% | 12.69% | -1.10% |
| SPG (Simon) | $205 | 14.46 | 15.08 | 120.51% | 46.02% | 19.50% |
| GOOGL (Alphabet) | $338 | 16.98 | 6.65 | 48.68% | 34.03% | 24.20% |
| GOOG (Alphabet) | $335 | 16.83 | 6.59 | 48.68% | 34.03% | 24.20% |
| DELL (Dell) | $567 | 33.00 | -256.46 | 0.00% | 12.02% | 57.70% |
| ANET (Arista) | $200 | 63.36 | 17.01 | 31.48% | 45.39% | 37.70% |
| CL (Colgate-Palmolive) | $87 | 34.17 | 293.24 | 267.37% | 20.97% | 4.90% |
| PANW (Palo) | $331 | 826.62 | 9.83 | 1.74% | 5.04% | 34.40% |
Verdict: Wait for Proof, Not Promises
Nike could be a good buy for investors who believe in the brand and trust management to execute the turnaround. And in a broad market selloff, Nike might get more grace from index committees.
But the S&P 500 and Dow are hovering near all-time highs. That shortens the leash for underperformers — especially a stock that now makes up just 0.4% of the Dow and sits near the median S&P 500 component weight.
Scenario Analysis
| Scenario | Probability | NKE Impact |
|---|---|---|
| Best Case: Turnaround gains traction, China stabilizes, margins recover above 12% | 25% | Dow seat retained; stock re-rates toward $55–$60 |
| Base Case: Slow recovery, Dow removal announced within 12–18 months | 50% | Additional 5–10% drawdown on index-exclusion flows |
| Worst Case: China deteriorates further, margins stay below 9%, dividend growth pauses | 25% | Break below $36.55; potential test of $30–$32 |
At this point, it's likely only a matter of time before Nike exits the storied Dow Jones index. Most investors may be better off waiting for concrete signals of a sustained turnaround — two to three quarters of margin expansion and China stabilization — before buying the stock.
⚠️ This analysis is for informational purposes only and does not constitute investment advice. All equity investments carry risk of loss, including the potential loss of principal.