The S&P 500 index currently yields a paltry ~1%, a level not seen in over two decades. For investors relying on dividend income, this is a desert of opportunity. However, beyond the index, there are oases of high yield for those willing to look deeper.
Today, we're dissecting three ultra-high-yield stocks that have caught the market's attention: AGNC Investment (AGNC), Ares Capital (ARCC), and Western Midstream Partners (WES). With yields ranging from ~8% to a staggering 13.5%, these aren't your average income plays. They are complex instruments—a REIT, a BDC, and an MLP—each with unique tax implications and risk profiles. Let's dive into the fundamentals to see if these yields are a trap or a treasure. 📌
The Contenders: A Closer Look at the Income Giants
AGNC Investment (AGNC): The 13.5% Monthly Payer
AGNC is a mortgage REIT (mREIT) that exclusively invests in Agency MBS—pools of home loans guaranteed by government-sponsored entities like Fannie Mae and Freddie Mac. This government backstop significantly reduces credit risk, but it doesn't eliminate risk. AGNC uses substantial leverage (borrowed money) to amplify returns, which cuts both ways. When interest rates fluctuate, the value of its portfolio and its book value can swing violently.
- Dividend: Monthly, yielding over 13.5%. It has maintained its current dividend for 75 consecutive months.
- The Bull Case: The company is currently generating mid-to-high double-digit leveraged returns on new investments, comfortably covering its dividend. Its cost of funding is stabilizing, which is a massive positive for an mREIT.
- The Bear Case: High leverage is a double-edged sword. A sudden spike in short-term rates or a steepening yield curve could compress book value and force dividend cuts, as we've seen in past cycles.
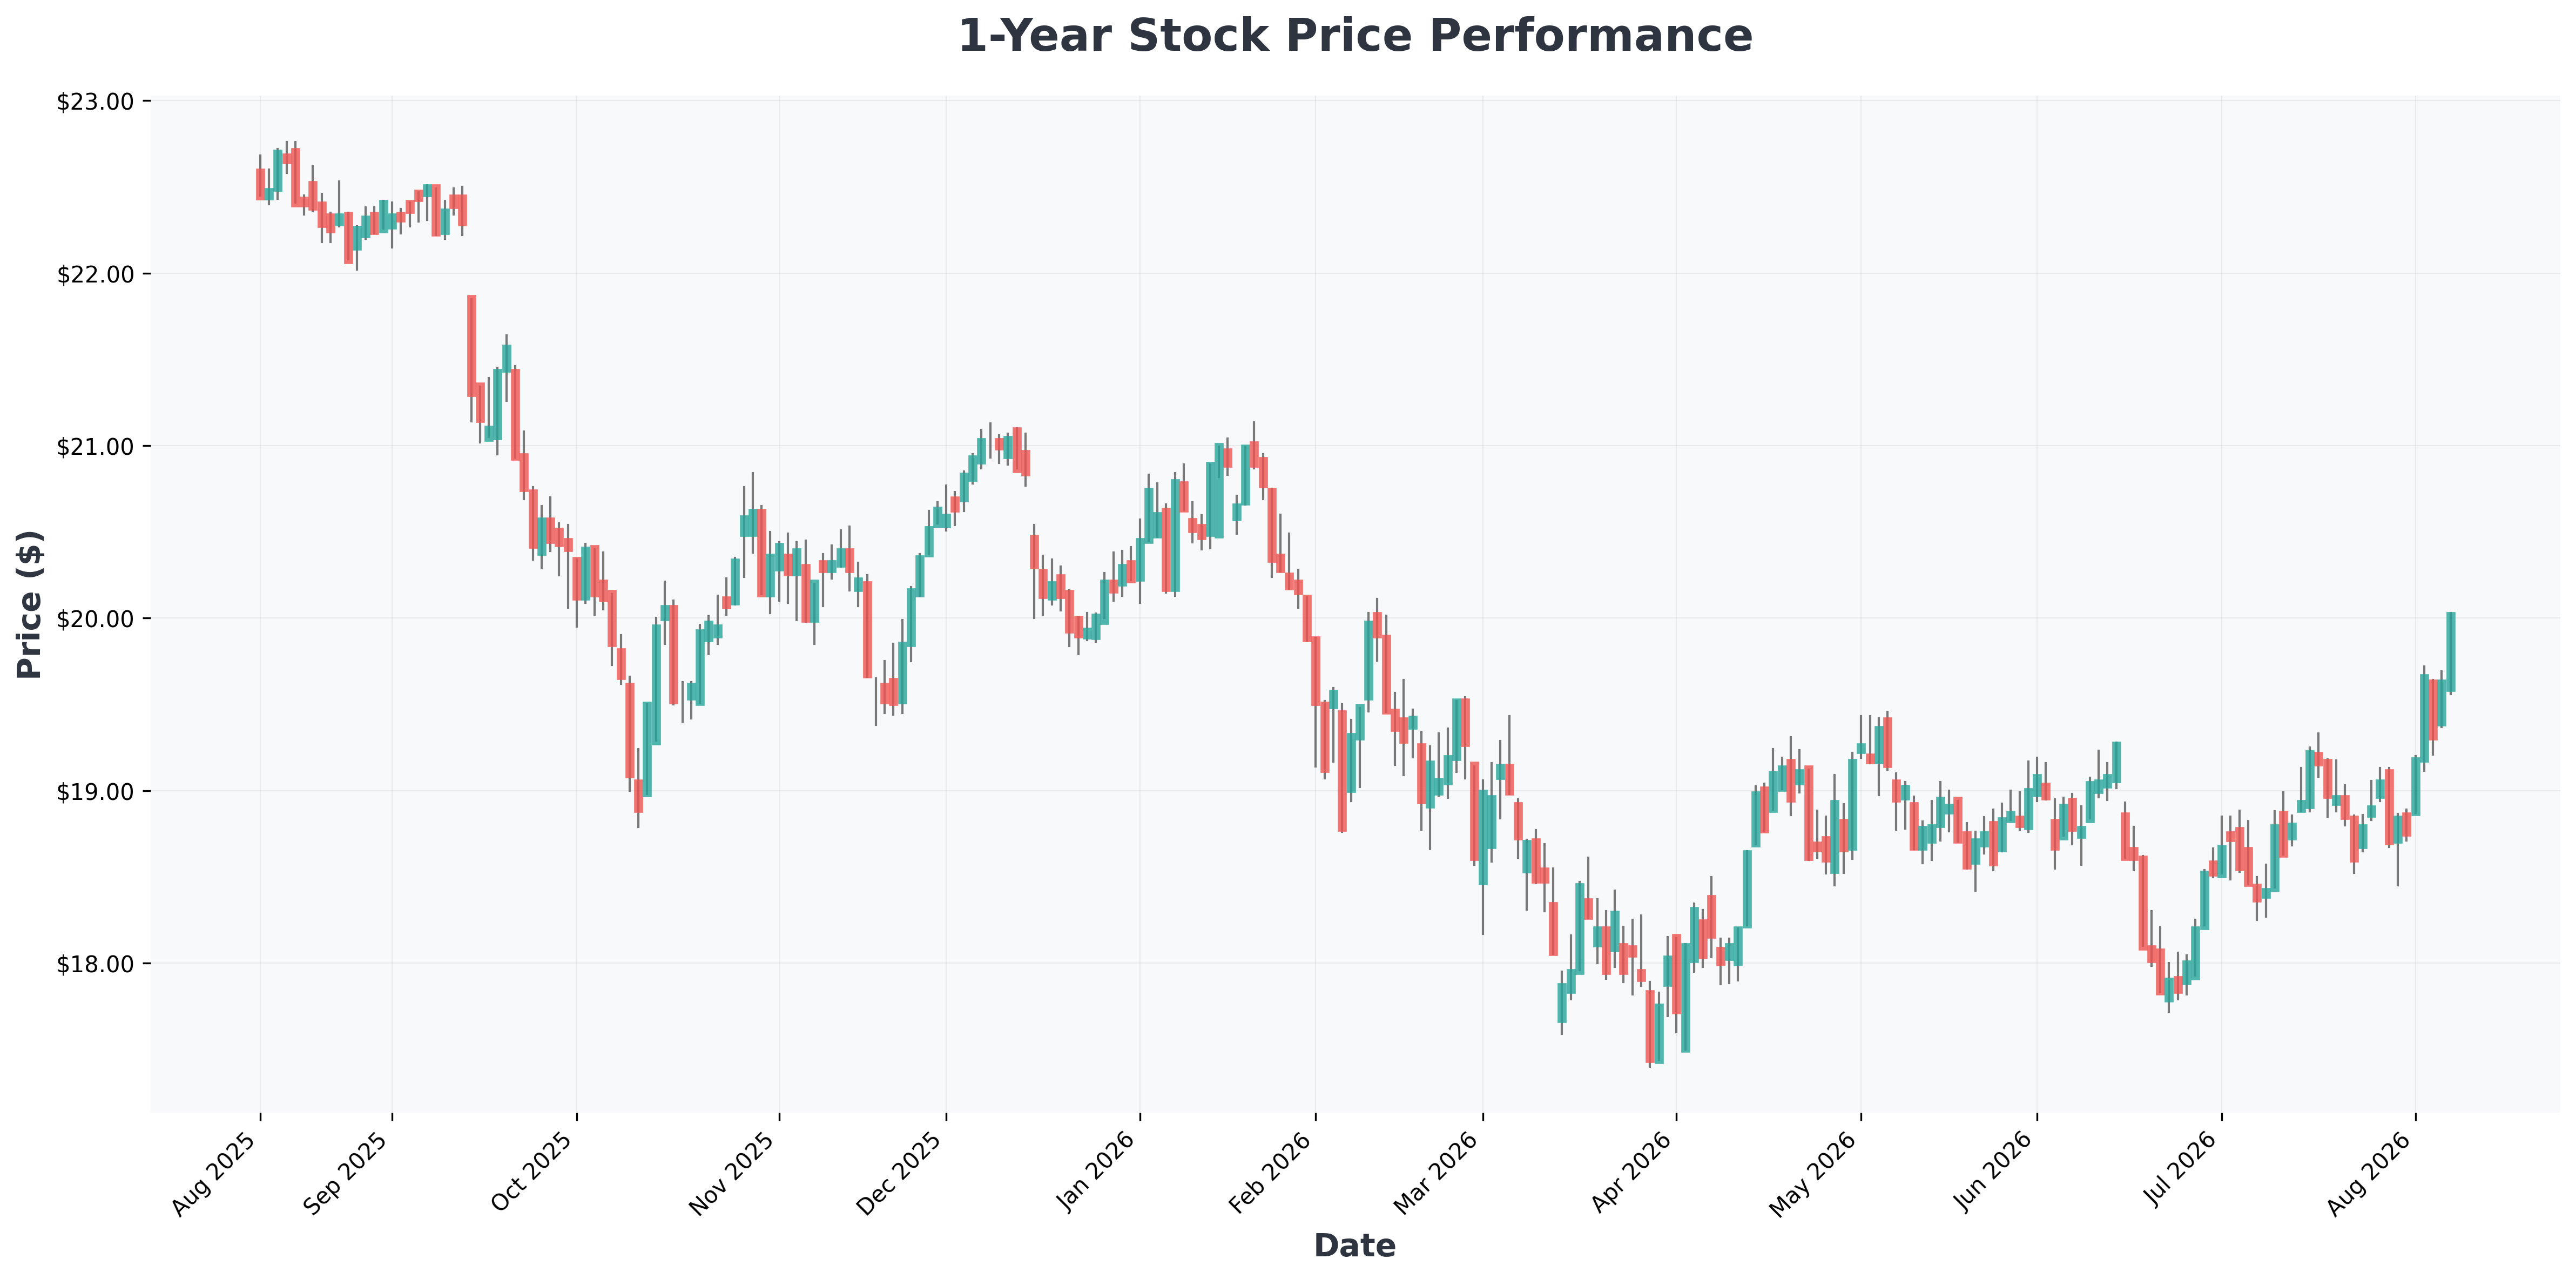

Ares Capital (ARCC): The BDC Powerhouse
Ares Capital is the largest publicly traded Business Development Company (BDC). It provides direct loans to private middle-market companies—firms with revenues between $500 million and $1 billion. These loans carry higher interest rates than traditional bank loans, but also higher risk. Ares has a stellar underwriting track record, with an annualized net realized loss rate of less than 0% across $73 billion of investments, outperforming both banks (-0.6%) and BDC peers (-1.1%).
- Dividend: Quarterly, yielding ~9.6%. It has paid a stable or growing dividend for 17 straight years.
- The Bull Case: The company's loss rate is historically low, showcasing its risk management. It has a massive cushion of excess taxable income ($1.38 per share) carried forward into 2026, providing a clear runway for dividend stability.
- The Bear Case: Core earnings dipped below the dividend in H1 2026 ($0.47 vs $0.48 per share). While covered by one-time gains and carryover income, this is a trend to monitor. A spike in middle-market defaults could pressure its portfolio.
The market is split on whether these yields are sustainable. Here's how the bulls and bears are framing the debate:
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| WES (Western) | $47 | 14.75 | 5.46 | 34.11% | 41.29% | 30.00% |
| AGNC (AGNC) | $11 | 5.39 | 1.19 | 19.80% | 95.61% | 0.00% |
| AGNCL (AGNC) | $25 | 0.00 | 2.78 | 19.80% | 95.61% | 0.00% |
| AGNCM (AGNC) | $25 | 0.00 | 2.77 | 19.80% | 95.61% | 0.00% |
| AGNCN (AGNC) | $26 | 0.00 | 2.85 | 19.80% | 95.61% | 0.00% |
| AGNCO (AGNC) | $26 | 0.00 | 2.82 | 19.80% | 95.61% | 0.00% |
| AGNCP (AGNC) | $25 | 0.00 | 2.78 | 19.80% | 95.61% | 0.00% |
| AGNCZ (AGNC) | $26 | 0.00 | 2.81 | 19.80% | 95.61% | 0.00% |
| ARCC (Ares) | $20 | 14.93 | 1.03 | 6.88% | 75.65% | 3.10% |
Western Midstream Partners (WES): The Energy Cash Cow
Western Midstream is a Master Limited Partnership (MLP) operating energy midstream infrastructure—pipelines and processing plants. Its business model is backed by long-term, fixed-rate contracts, providing highly predictable cash flows. Since resetting its distribution in 2020, WES has increased it by a massive 193%.
- Distribution: Quarterly, yielding ~8%. It expects to generate $2.1-$2.3 billion in distributable cash flow this year.
- The Bull Case: The company has ample free cash flow ($1.1-$1.3 billion) to fund growth projects like the North Loving II plant and Pathfinder Pipeline. It also has the flexibility for accretive acquisitions (like the $1.6 billion Brazos Delaware purchase).
- The Bear Case: As an MLP, it issues a K-1 tax form, which can complicate tax filing. Its growth is tied to energy production levels; a significant slowdown in drilling could impact volumes.