After years of underperformance, Verizon Communications (NYSE: VZ) has flipped the script in 2026. 📌 The telecom giant is up more than 25% year-to-date, trading around $48.05 with a market cap of roughly $201 billion — and for the first time in years, the bulls have a real narrative to work with.
Under new CEO Dan Schulman (appointed October 2025), Verizon is beating quarterly expectations, expanding margins, and integrating the Frontier Communications acquisition to supercharge its fiber footprint. With a 5.78% dividend yield and a Moneyball Superscore of 70/100, the question on every investor's mind is simple: Is this the year's best telecom stock?
Let's break down the fundamentals, the risks, and the bull vs. bear case. 🚨
The Turnaround Nobody Saw Coming
The most striking data point from Verizon's Q2 2026 report is 184,000 postpaid net phone additions — a stunning reversal from a net loss just a year ago. This is the kind of metric that signals real operational momentum, not just financial engineering.
What's Driving the Beat?
- Leadership: Dan Schulman's boardroom-to-CEO transition has brought a sharper focus on execution and cost discipline.
- Frontier Deal: Fiber broadband connections are up 43% year over year, giving Verizon a credible fixed-wireless and broadband growth engine.
- Cost Cuts: Management is targeting $5 billion in cuts in 2026 alone, which is flowing directly into EBITDA and margin expansion.
The Competitive Landscape
T-Mobile and AT&T are both performing solidly, but neither has the same operational momentum Verizon is showing right now. For readers tracking broader tech sector rotations, our breakdown of Meta's AI wearables vs. Apple's foldable iPhone strategy shows how platform battles in adjacent sectors can reshape capital flows — a dynamic that also affects telecom positioning.
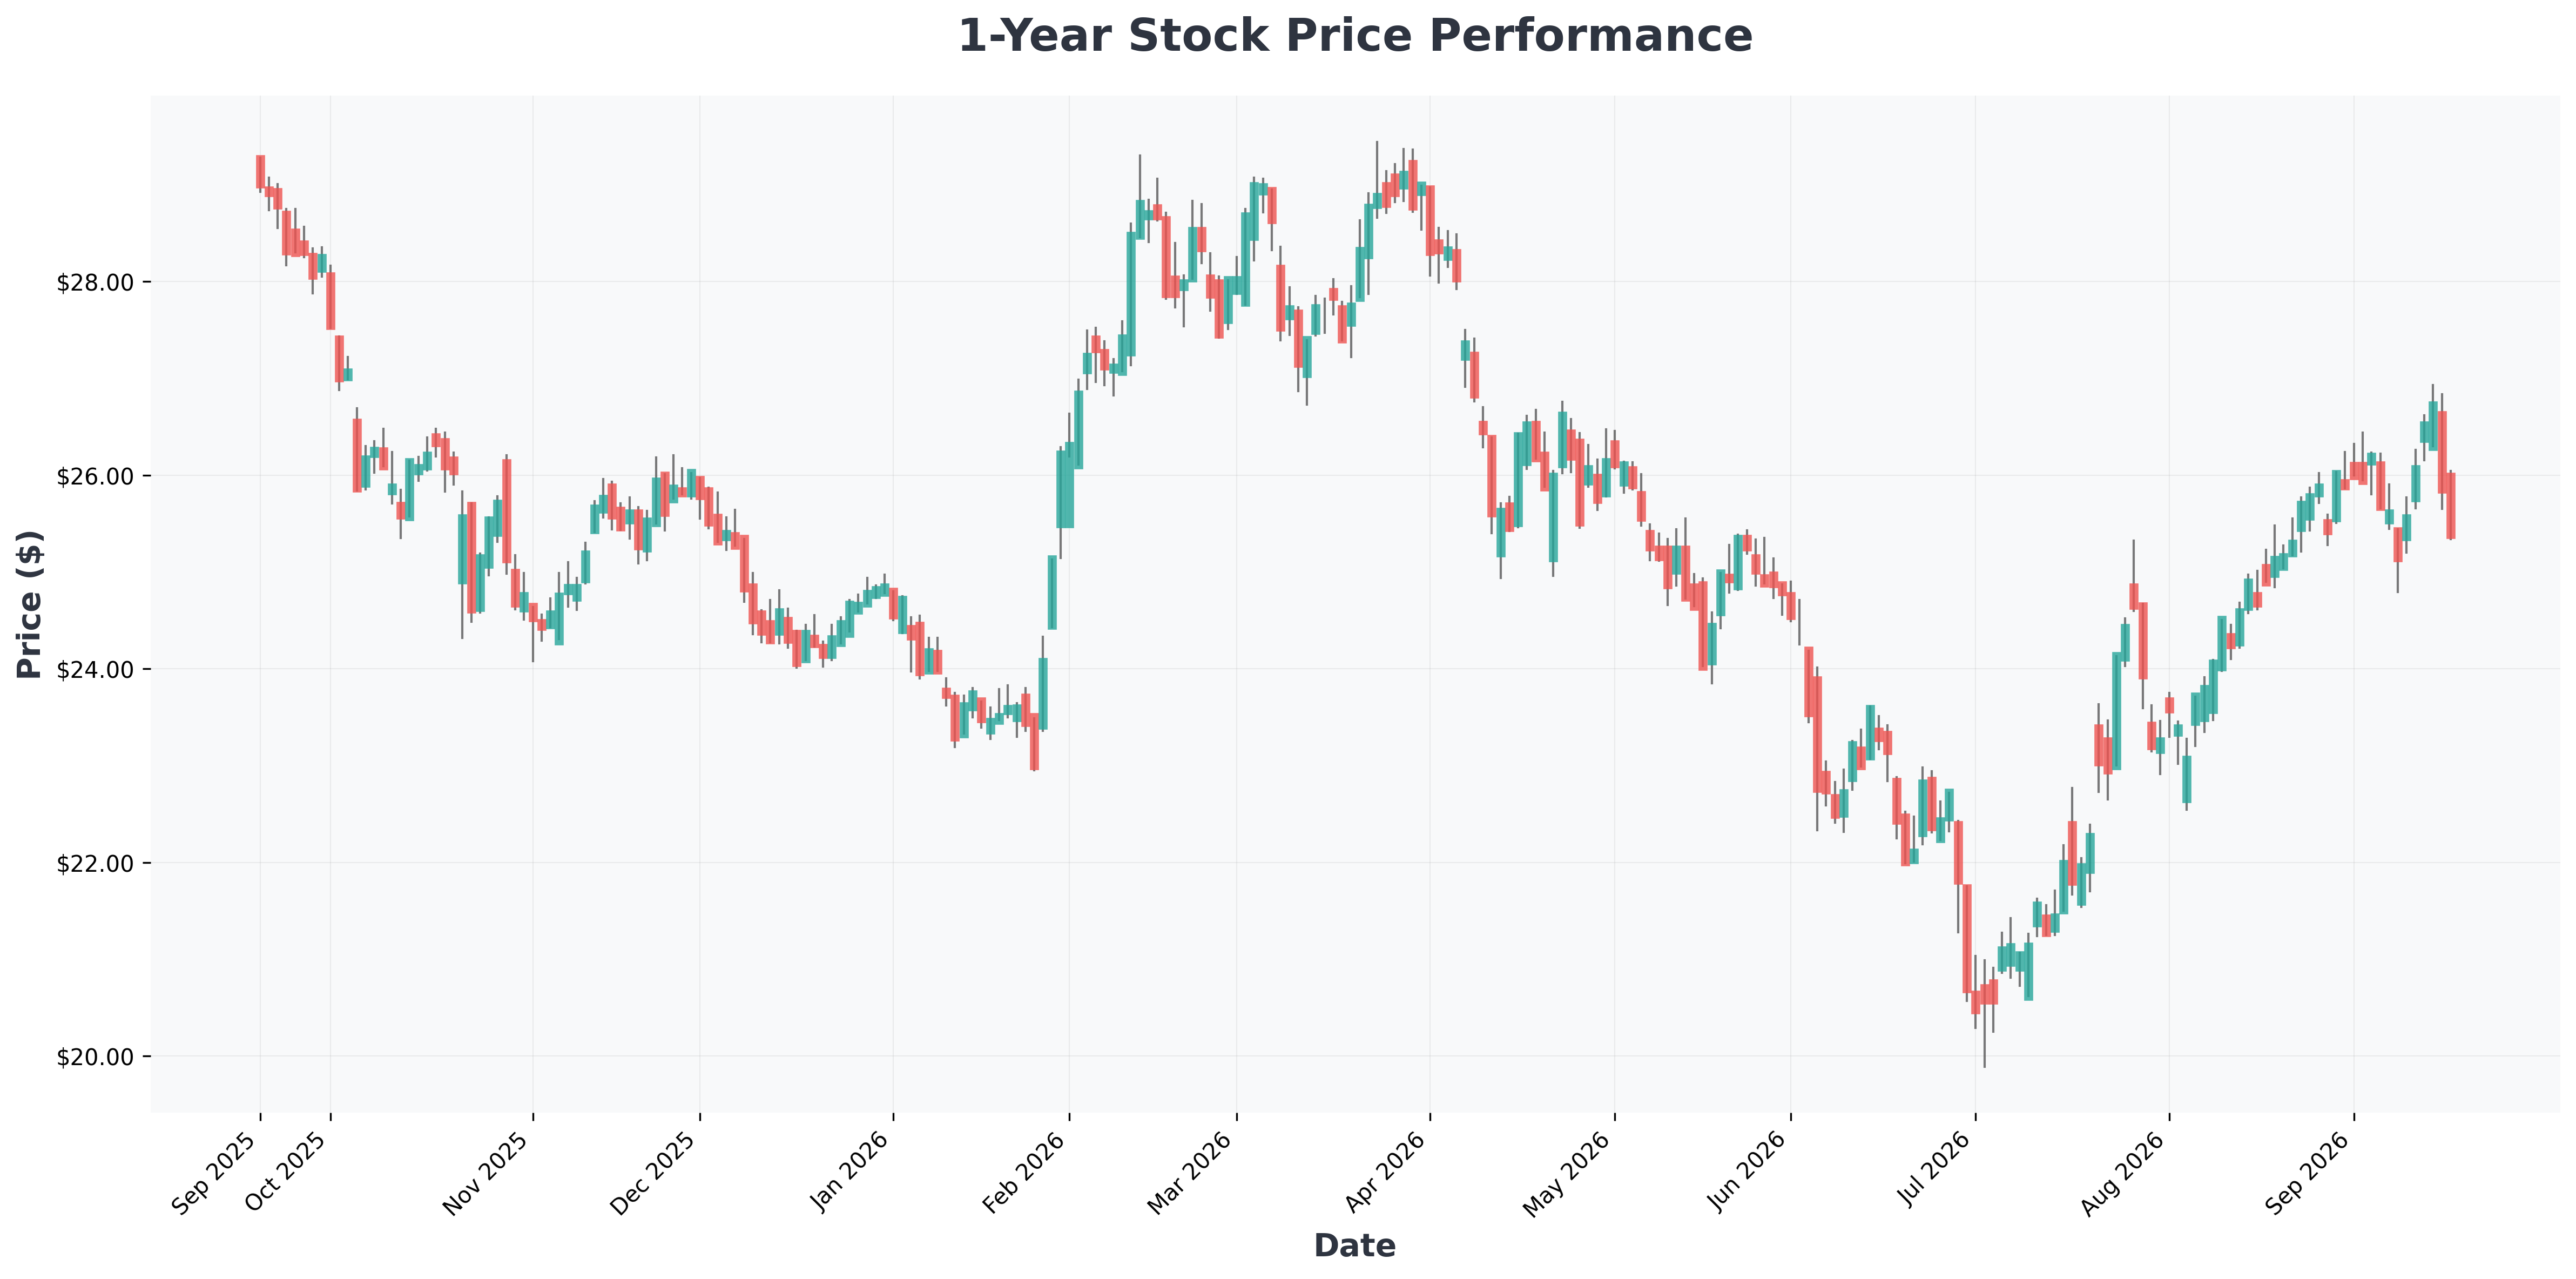
Technical note: VZ's 52-week range sits at $38.39–$51.68. The stock is currently testing the upper half of that band, with the $51–$52 zone acting as a key resistance level. A clean break above it on volume could open the door to new highs, while failure to hold $45 would signal a bull trap.
The market is split on whether Verizon's rally has legs. Here's how the two camps are framing it:
Key Data at a Glance
| Metric | Value |
|---|---|
| Ticker | NYSE: VZ |
| Current Price | $48.05 |
| Today's Change | -0.59% (-$0.29) |
| Market Cap | $201B |
| 52-Week Range | $38.39 – $51.68 |
| Volume (today) | 10.2M |
| Avg Volume | 25.8M |
| Gross Margin | 45.71% |
| Dividend Yield | 5.78% |
| Moneyball Superscore | 70/100 |
Why the Valuation Still Looks Reasonable
Despite the 25% run, VZ is not expensive relative to its earnings power. If the company sustains its current growth trajectory — expanding EBITDA, growing fiber subscribers, and cutting costs — the stock could still be fairly valued or even slightly undervalued.
For context on how quickly sentiment can shift in broader markets, look at our recap of last week's futures dip after a two-day rally, with Intel plunging 12% on weak guidance. Telecom has been a relative safe haven in that kind of volatility.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| T (AT&T) | $26 | 8.42 | 1.59 | 18.34% | 24.79% | 2.30% |
| TMUS (T-Mobile) | $167 | 17.50 | 3.19 | 17.99% | 25.22% | 7.90% |
| TpC (Tutor) | $86 | 36.88 | 3.71 | 13.74% | 7.22% | 19.20% |
| VZ (Verizon) | $48 | 12.50 | 1.92 | 15.84% | 23.00% | -0.70% |
Scenario Analysis: Where Does VZ Go From Here?
🟢 Best-Case Scenario
- Postpaid phone growth continues above 150K per quarter.
- Frontier integration delivers the full $5B cost savings ahead of schedule.
- Dividend increases again in 2027, drawing income investors.
- Price target range: $58–$62 over the next 12 months.
🔴 Worst-Case Scenario
- Competitive pressure from T-Mobile and AT&T compresses ARPU.
- Fiber capex overshoots, pressuring free cash flow.
- Rate environment turns unfavorable for high-yield dividend names.
- Downside risk: retest of $40–$42 support zone.
The Bottom Line
Verizon is no longer a sleepy dividend play — it's a comeback story with real numbers behind it. The combination of new leadership, accretive M&A, aggressive cost-cutting, and a 5.78% yield makes VZ one of the most compelling telecom setups of 2026. But as always, position sizing and risk management matter more than any single thesis. Do your own due diligence before allocating capital. 💡